Mortgage Insurance Order: What Trump’s PMI Plan Means for You
Trump signed a housing order on Thursday, and the mortgage insurance order is the part most borrowers will care about. It tells the agency that oversees Fannie Mae and Freddie Mac to build a pilot that cancels private mortgage insurance (PMI) on its own once you have enough equity. It also tries to make refinancing cheaper. The headlines made it sound like a done deal.
So I read the order itself, then the coverage from CNBC, Yahoo Finance and Realtor.com. The order is real, but it is more of a to-do list for regulators than a switch that flips on Monday. Here is what it says, what I think it could mean for your wallet, and what I would do this week.
What the mortgage insurance order says
The official title is “Decreasing Housing Costs for the American People,” dated October 22, 2026. It has four moving parts.
| Part | What it asks for | Timing |
|---|---|---|
| PMI cancellation | A Fannie and Freddie pilot that cancels mortgage insurance automatically once you have enough equity | Only for loans made after the pilot starts |
| Title insurance on refinances | Turn the current title waiver pilot into a permanent, nationwide program | No date given |
| Manufactured housing | A task force to speed up factory-built homes | Recommendations due within 180 days |
| USDA and VA direct loans | Lower interest rates on the small number of loans those agencies make themselves | Depends on the law and funding |
The first two are the ones that touch everyday borrowers, so I will stick with those.
How PMI cancellation works today
PMI usually shows up when you put down less than 20% on a conventional loan. It protects the lender, not you, but you pay for it every month. Freddie Mac estimates the cost at $30 to $70 a month for every $100,000 you borrow, according to Yahoo Finance. And it is not rare. Urban Institute data says 36% of conventional borrowers paid PMI in 2024, up from 25.4% in 2016.
The current rules come from the Consumer Financial Protection Bureau’s PMI guide. In short, there are two ways out:
- You ask at 80%. You can request cancellation in writing once your balance is scheduled to reach 80% of the home’s original value. You need a good payment history, no second mortgage, and proof the home has not lost value.
- It drops itself at 78%. Your servicer has to end PMI when the balance reaches 78% of the original value, as long as you are current on payments.
That “original value” detail is the catch. It is usually the lower of your purchase price or your appraisal, so a home that has gained value does not speed things up by default. You can still ask for earlier cancellation based on today’s value with an appraisal, and CFPB says lenders’ investor guidelines may allow it. But that means paperwork and an appraisal fee. Honestly, I suspect many people never bother.
What the mortgage insurance order could change for PMI
The pilot would look at the current market value of the home using automated valuation models, which are software estimates, instead of requiring you to order an appraisal. The servicer would also have to tell you promptly when you may qualify and cut down on the paperwork. Realtor.com describes the goal as ending the need for “excessive documentation and costly appraisals.”
I like that part. Because the servicer does the work, the cancellation does not depend on you remembering to ask. That is where most of the savings could come from.
To see how big the gap could get, I ran a rough example. This is my math, not a number from the order:
- A $400,000 home with 10% down means a $360,000 loan. At 7.32%, the rate Freddie Mac reported on October 23, the schedule reaches 80% of the original price after about 8.7 years.
- If the home gains 3% a year, the same balance equals 80% of the current value after about 3 years.
- At $150 a month in PMI, which sits inside Freddie’s range for that loan size, the 5.7-year gap adds up to roughly $10,000.
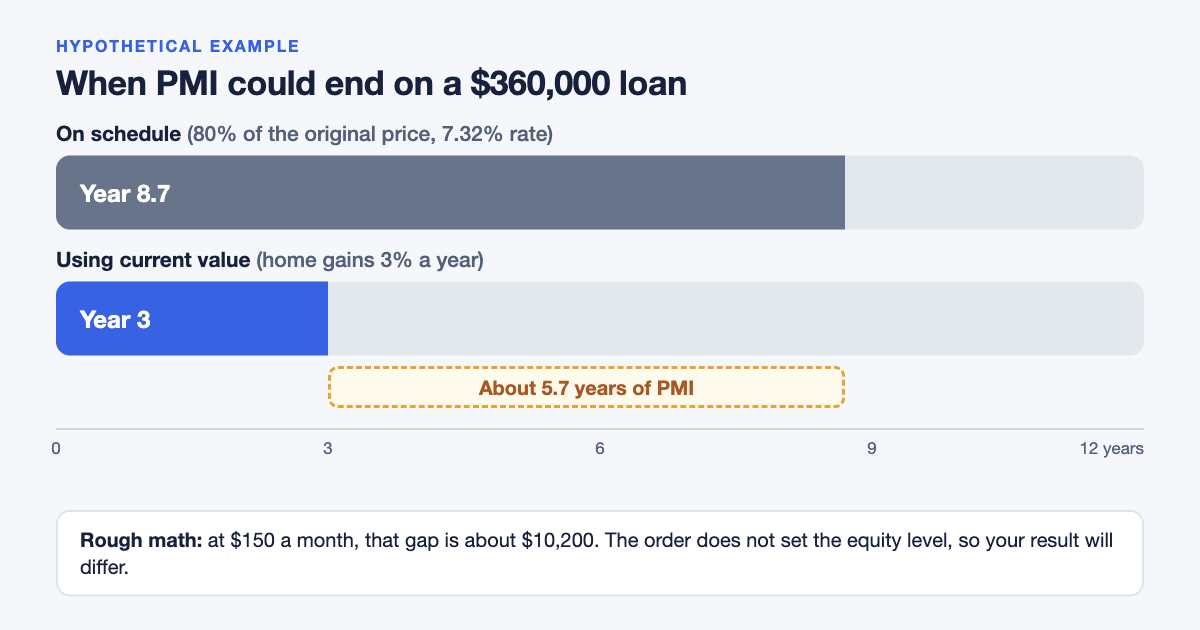
Your numbers will differ. The order does not say what equity level counts, and home prices do not always rise. Still, it shows why switching from original value to current value is the detail to watch.
The fine print in the mortgage insurance order
This is the part that changed how I read the news. The PMI section says the FHFA director “shall, if he determines that it is in the best interests” of Fannie, Freddie and the public, tell them to start the pilot. That wording leaves the decision with one official, and it does not set a start date.
- It only covers future loans. The pilot applies “only to mortgages made after the establishment of the pilot program.” If you already have a loan, it does not change your rules.
- Safety standards still apply. The order asks for payment-history requirements and says cancellation must fit “financial safety and soundness.”
- It creates no new right. Section 6 says the order does not give anyone a legal claim against the government.
- Experts want more details. CNBC quotes Keith Gumbinger of HSH saying the effect is hard to judge without them. The PMI industry’s trade group said it is already delivering lower costs.
None of this makes the order useless. Pilots are how these programs usually start. But I would treat it as a plan, not a benefit you can count on yet, especially with the midterm elections less than two weeks away and housing costs on everyone’s mind.
FHA loans are different too. They carry their own mortgage insurance on every loan, and none of the coverage I read says this pilot touches them.
Refinancing: the title insurance part
When you refinance, the lender usually requires a lender’s title insurance policy, and title fees tend to be the largest part of closing costs, according to the Urban Institute report CNBC cites. An FHFA pilot already lets Fannie and Freddie accept an automated title review instead. It was limited to loans under 80% loan-to-value in a handful of states, and a former FHFA director estimated it saved $500 to $1,500 in closing costs.
The order wants that pilot to become a permanent, nationwide program. It also tells the director to consider extending it above 80% loan-to-value, waiving appraisals for certain refinances that lower your payment, and passing every dollar of savings to the borrower. One catch: “consider” is not the same as “do.”
The title industry has pushed back a little. The American Land Title Association says affordability is critical, but any change should keep the protections that guard against fraud. That is a fair worry, since a title problem tends to show up years later.
Is it a big deal right now? Probably not for most people. Freddie Mac put the 30-year rate at 7.32% on October 23, and CNBC reports refinance demand down 59% from a year ago. Another rough example of mine: if a refinance saves you $200 a month and costs $5,000 to close, you break even in 25 months. Knock $1,000 off the closing costs and it takes 20. That helps, but the rate still decides whether a refinance makes sense.
What I would do this week
| If you… | Then I would… |
|---|---|
| Pay PMI on a conventional loan today | Call your servicer and ask what they need to cancel it. Check your balance against your original value, and ask how they treat today’s value |
| Plan to buy soon | Ask lenders for the PMI cost with several down payment sizes. Do not plan around the pilot, since it only covers loans made after it starts |
| Think about refinancing | Ask your lender whether it can use a title waiver or an automated title review today, and compare total closing costs, not just the rate |
| Have an FHA loan | Keep your usual plan. The coverage I read says nothing about FHA mortgage insurance |
I would also watch for two things: whether the FHFA announces a start date for the pilot, and what equity level it sets. Those two details will tell us if this is a real change or mostly a headline. If you are following rates in Canada too, I covered the Bank of Canada’s October 28 decision in an earlier post.
Quick answers
Does this cancel my PMI right now? No. The pilot has no start date yet, and it covers only loans made after it launches.
Can I already get rid of PMI? Yes. You can ask your servicer once you reach 80% of the original value, or ask about using today’s value, which usually needs an appraisal.
Will my closing costs drop on a refinance? Possibly, if the title program expands and your lender uses it. The order does not guarantee it.
The short version
Trump’s mortgage insurance order asks regulators to build a pilot that cancels PMI automatically, but only for future loans and only if the FHFA director decides to start it. If you pay PMI now, call your servicer and ask about cancellation yourself instead of waiting.